NVIDIA: The Ultimate Self-Licking Ice Cream Cone
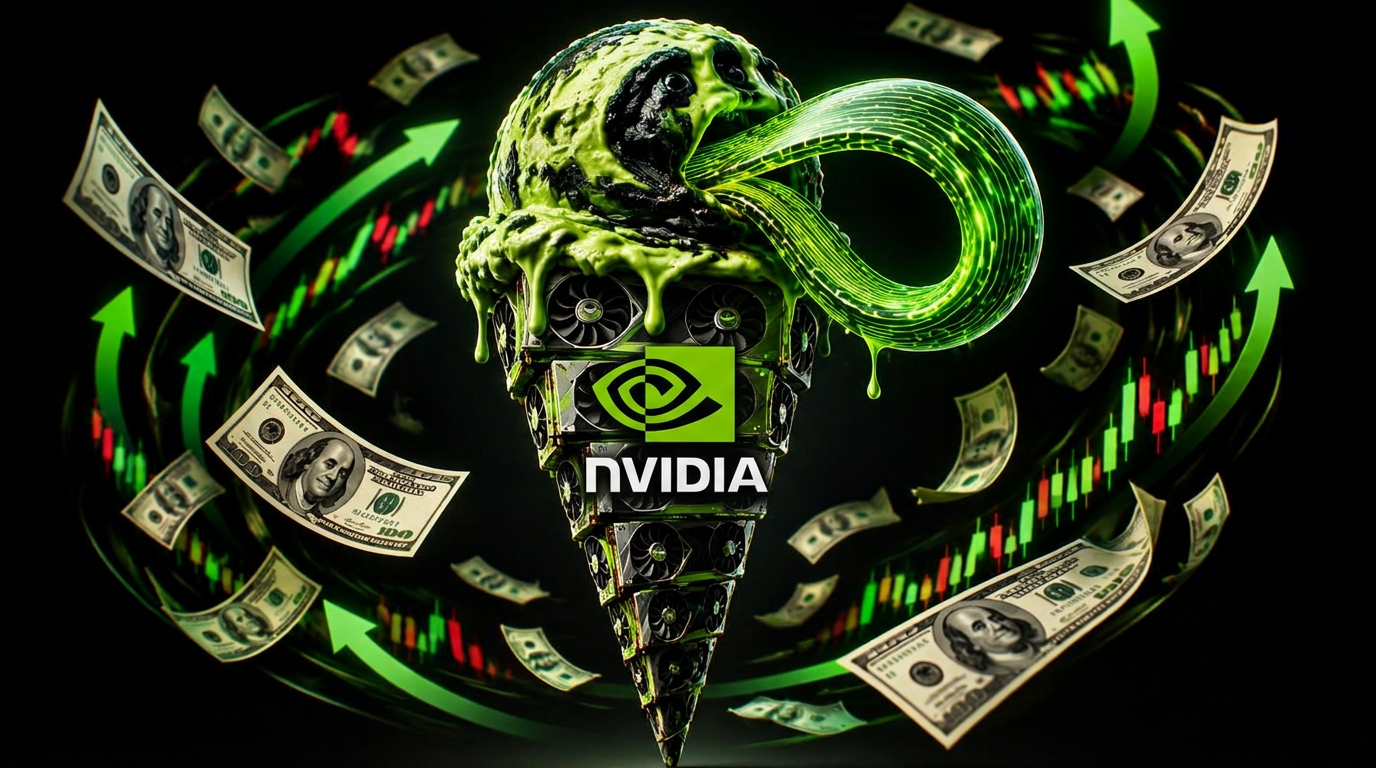
There is an old phrase that describes a self serving machine: the self-licking ice cream cone. It feeds itself, justifies itself, and grows itself. Look closely at NVIDIA in 2026 and you’ll see the most profitable version ever built. The next scoop gets served on Wednesday, November 18, 2026, when NVIDIA reports earnings after the close.
1. The Scoop: NVIDIA Finances Its Own Customers
AI data centers cost billions. Many of the companies racing to build them — GPU cloud providers, AI labs, sovereign AI projects — don’t have that cash sitting around.
So NVIDIA helps. Through equity stakes, investment commitments, capacity guarantees and partner financing, NVIDIA puts money into the very companies that turn around and order… NVIDIA GPUs.
NVIDIA invests in the customer → the customer buys NVIDIA chips → NVIDIA books the sale as revenue.
The money leaves NVIDIA’s left pocket and comes back into its right pocket — this time labeled “record data center revenue.”
2. The Cone: Revenue Becomes Profit, Profit Becomes Cash
NVIDIA’s margins are the envy of the hardware world. Every GPU sold throws off enormous profit. That profit piles up as cash — far more than the company needs to run its business.
Which brings us to the second lick.
3. The Lick: The Stock Buyback
NVIDIA has authorized buybacks in the tens of billions of dollars. Buying back stock shrinks the share count, which lifts earnings per share — even if total profit stood still.
Higher EPS → higher stock price → a richer NVIDIA with a more valuable currency to… invest in more customers.
4. The Full Loop
- NVIDIA invests in or backs an AI customer.
- The customer uses that money (and borrowing it unlocks) to buy NVIDIA GPUs.
- NVIDIA reports blowout revenue and margins.
- Cash piles up; NVIDIA buys back its own stock.
- EPS and the share price rise; NVIDIA’s stakes in customers look even more valuable.
- Repeat — bigger each time.
The cone licks itself. And every lick makes the cone taller.
5. Why It’s Brilliant
- Lock-in: customers funded by NVIDIA build on CUDA and NVLink — and stay for a decade.
- Demand shaping: NVIDIA helps create the buyers for its next product cycle.
- Competitive moat: AMD and custom-chip rivals can’t easily match a supplier that also brings the money.
- Shareholder rewards: buybacks return cash and support the stock.
6. Where the Ice Cream Could Melt
Circular money is powerful on the way up — and dangerous on the way down. Traders should watch for:
- End-demand reality: are AI apps earning enough to pay for all this compute, or is the spending mostly funded by NVIDIA and debt?
- Customer credit: heavily leveraged GPU clouds are the weakest link if rental prices fall.
- Revenue quality: how much of the growth traces back to NVIDIA-backed buyers?
- Buyback vs. growth: if buybacks start to outpace real revenue growth, that’s the cone licking faster than it’s filling.
- History: vendor financing looked genius in the 1999–2000 telecom boom — until it didn’t.
7. What It Means for Penny Stock Traders
As long as the loop spins, NVIDIA headlines keep lighting up the AI penny stocks that trade in sympathy — data center, power, cooling and AI software names. When the cone wobbles, those same small caps fall first and hardest.
That’s exactly why we built our scanner to only alert on stocks that are actually rising — not just on noisy volume. See our top 10 AI penny stocks updated daily.
8. The Bottom Line
NVIDIA funds the customer. The customer buys the chips. The chips become profit. The profit buys back the stock. The stock funds the next customer.
It’s the ultimate self-licking ice cream cone — delicious as long as the freezer stays cold.
Not financial advice. Opinion and commentary only.